
The Importance of Preventive Care

Don’t wait until you’re sick to see your doctor. Preventive care isn’t just about avoiding illness—it’s about building a foundation for lifelong health.

What is Preventive Care?

Typically, you visit the doctor when you’re sick or something just doesn’t feel quite right. While you should always seek help in those instances, preventive care means taking proactive steps—like regular check-ups, screenings, and immunizations—to protect your health before problems arise.

These visits support early detection and give you and your doctor the opportunity to work together toward your personal health and wellness goals. During a preventive care appointment, your doctor will determine which tests or screenings are appropriate based on your age, gender, health status, and family history.

What’s Typically Covered?

Physical Exams

During a physical exam, your doctor will observe, listen, and gently examine your body to help identify symptoms, assess underlying conditions, and determine if further testing is needed. You’ll also have the chance to discuss any concerns, review your medical history, and review current medications.

Immunizations

Immunizations (or vaccinations) are one of the most effective ways to protect yourself from infectious diseases. They help your body build antibodies that recognize and fight illness if you’re exposed later.

Common immunizations include flu and tetanus shots, the measles, mumps, and rubella (MMR) vaccine, and hepatitis A and B vaccines.

Screenings

Member Moment

Meet Ginger
“It’s very hard to look your kids in the eye and tell them that you have cancer. When they told me I was cancer free, I felt like I could breathe for the first time. I had great insurance, and I know our members do too, so I hope this is encouraging them to get their yearly checkups.” – Ginger, Member since 2013

Watch Ginger’s full member moment here.

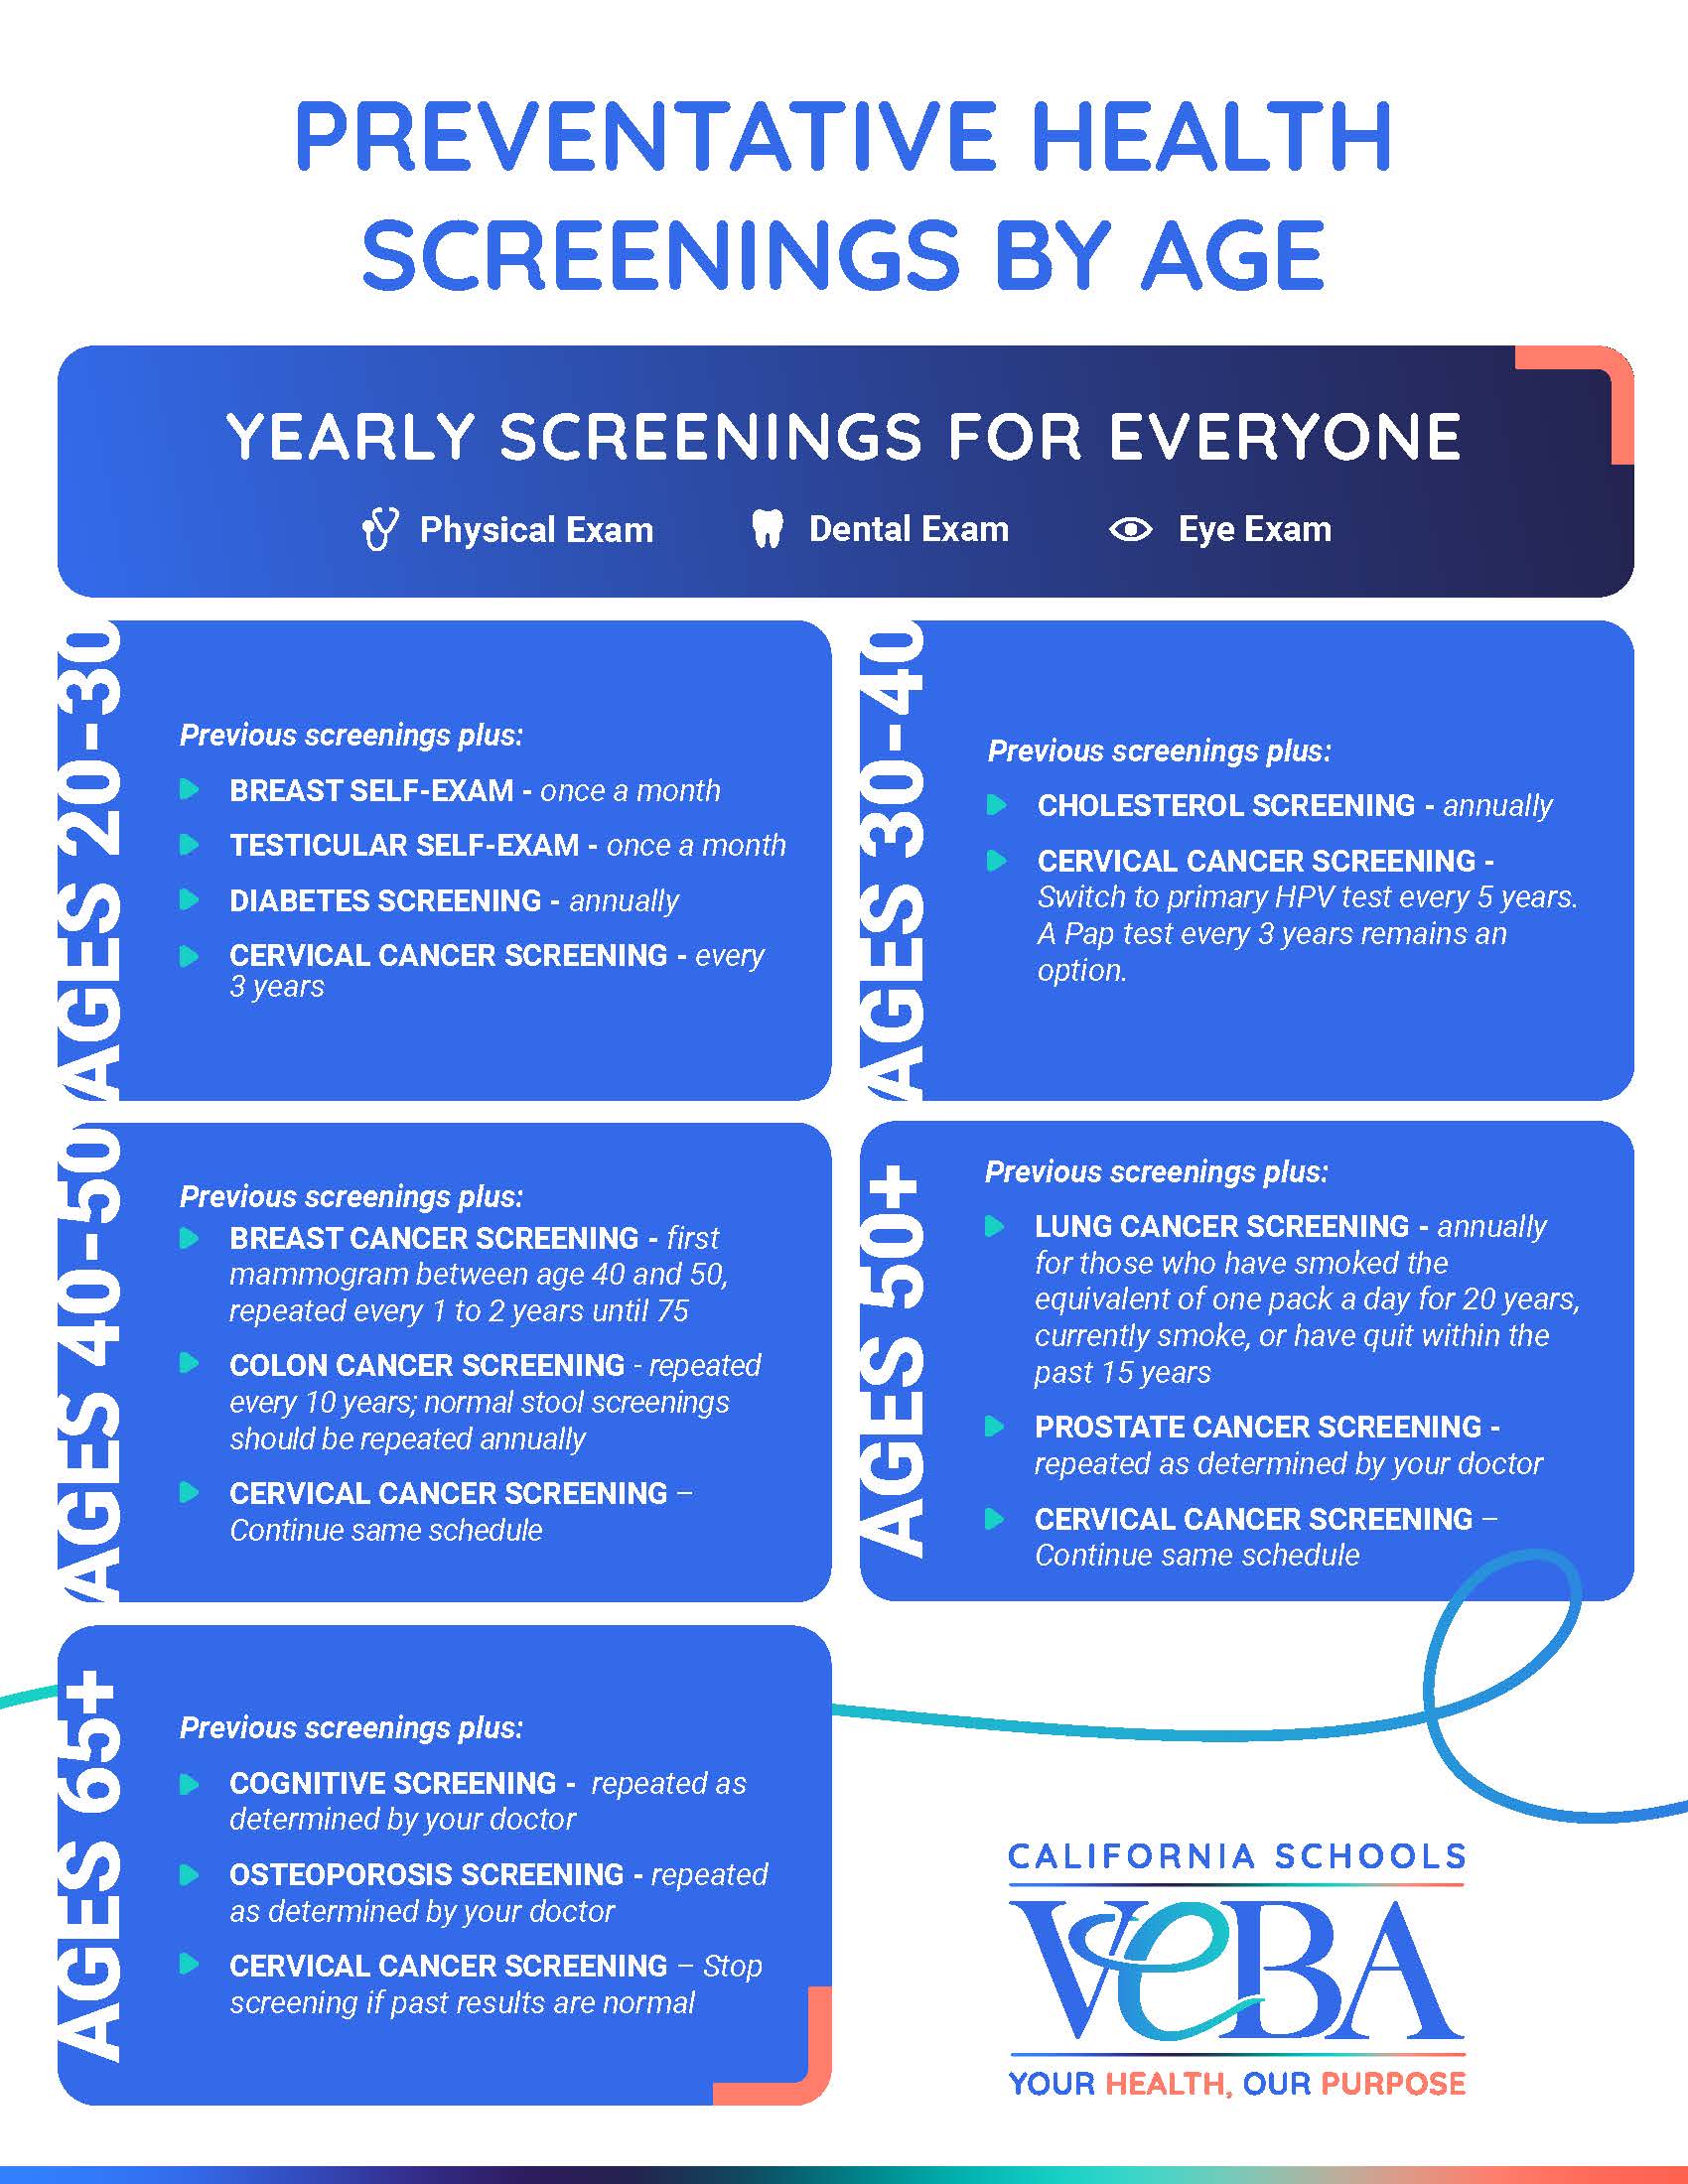
Screening tests help detect certain diseases before symptoms appear. Early diagnosis often leads to better outcomes and can prevent or delay complications. Use the infographic below to see which screenings may be recommended for your age group.

Preventative Health Screenings by Age, CalVEBA Infographic

Disclaimer:

This is a general guide for average-risk individuals. Higher risk may require more frequent screening. Consult with your health care provider.

Appointment Scheduling Tips

Preventive care appointments are usually covered at no cost with in-network providers. Check your plan documents to confirm coverage and costs.

Make the most of your doctor’s appointments by being well-prepared and organized using our Appointment Ready: Your Doctor’s Visit Prep Guide.

Here are some tips to help you get started:

Before Your Appointment:

  • Make a List: Bring a list of medications and jot down questions or concerns.
  • Bring Your Insurance Card: Download and save to your mobile wallet for easy access.

During Your Appointment:

  • Arrive Early: Arrive 10-15 minutes early to complete any paperwork. 
  • Dress Comfortably: Wear a shirt or loose-fitting sleeves for your blood pressure check. 
  • Use Your List: Review your list with your doctor. 
  • Speak Your Mind: Your time and health are valuable! 

After Your Appointment:

  • Follow Through: Take prescribed medications as directed and schedule any recommended follow-ups or screening. 
  • Speak Up: Report new symptoms or concerns promptly.  
  • Get a Second Opinion: If you’re unsure about a diagnosis or treatment plan, CalVEBA members can access second opinions from world-renowned specialists at no cost through our partnership with Teladoc Medical Experts. 

Preventive care can help you stay ahead of health issues and maintain overall well-being.

Download our Appointment Ready: Your Doctor’s Visit Prep Guide today and start planning for your next preventive care visit!


Thank you to our content partners at Sharp HealthCare and Healthwise.

Need help to schedule an appointment or have questions about your medical coverage? Contact the California Schools VEBA Advocacy Team here or call 888-276-0250.

Trusting Your Gut When It Comes to Health Care 

When choosing your health care team and your health plan, you want to make decisions based on reliable and sound information. This information can come from different sources like provider reviews, plan certifications, cost analysis, and more. There’s another source of insight that’s often overlooked: your own instincts. Your gut can help you evaluate your experiences and whether your needs are truly being met. When you listen to that inner voice, you’re better equipped to make the right decisions for your health.

Feel Seen & Heard: What Makes a Good Doctor-Patient Relationship?

Studies have shown that a good provider-patient relationship can lead to better outcomes, fewer errors, lower costs, and a more positive experience overall. But what does a good relationship look like?

Experts have identified five key pillars:

  • Respect
  • Engaged curiosity
  • Focused listening
  • Mutual participation
  • Provider self-awareness

Roundtable Discussion

These pillars can’t be objectively measured, but rather, they’re felt between a provider and patient. If you feel heard, respected, and involved in your care, that’s a sign you’re in the right hands. Watch CalVEBA’s roundtable to hear medical experts talk about the “green flags” to look for in a provider.

Save Money & Reduce Stress: Staying In-Network Matters

Once you’ve found a provider that you feel confident and comfortable with, you’ll want to pay attention to your health plan’s network. Providers can leave or join networks throughout the year. Staying in-network usually means lower out-of-pocket costs. If your preferred provider is out-of-network, that may be a sign to start comparing plan options during Open Enrollment.

Time to Check-In: How Do You Feel About Your Health Plan?

Studies show that many insured adults face challenges with their health plan carriers and those in poorer health often struggle even more. This Open Enrollment season, take a moment to reflect:

  • Has it been easy to get information from your health plan?
  • Do you feel valued as a member?
  • Are your needs being met?

Your Experiences Matter: Let Your Feelings Guide You

From choosing a doctor to choosing the right health plan for you, health care decisions can be stressful. They can affect your health, finances, and peace of mind. While it might feel risky to factor in your emotions, your feelings are a valid and powerful tool. As you evaluate your feelings about your health care experiences, ask yourself:

  • Do you like your doctor?
  • How did your last visit make you feel?
  • Did you feel listened to and respected?
  • Is it easy to get an appointment?
  • What did you like or dislike about your experiences with doctors, hospitals, pharmacies, and your health insurance carrier over the past year?
  • Can you refill prescriptions without hassle?
  • Are billing and claims questions answered clearly?
  • Do you feel confident in the care and coverage you’re receiving?

Take the Next Step: Turning Insight into Action

Once you’ve taken the time to reflect on your experiences and feelings, the next step is knowing where to turn for support. Whether you’re looking for a provider who truly listens or trying to navigate your health plan options, CalVEBA offers tools and resources to help you make informed, confident choices.

Your Open Enrollment Checklist

Plan Smart

Choosing a health care plan is one of the most important decisions for yourself or your family each year.

Open Enrollment is when people in the U.S. can renew, change, or cancel their health care plan and make other adjustments, like adding or removing dependents.

Although health care is essential for your well-being, navigating it can be complicated. Preparing for Open Enrollment is essential so you can choose the right health care plan for you. Let this checklist guide you as you prepare for the next Open Enrollment.

How to Get Ready

1. Review your current plan coverage 

Understanding your current plan coverage allows you to evaluate how well it aligns with your health care needs. By reviewing the services, treatments, prescription medications, and costs covered under your existing plan, you can identify gaps or areas where your current coverage may be insufficient. This knowledge will help you make informed decisions when comparing plans during Open Enrollment. 

Familiarizing yourself with your current plan’s provider network is crucial if you have preferred doctors, hospitals, or specialists you want to continue seeing. Check if your current health care providers are in-network or out-of-network under your current plan. This information will help you determine if you need to switch to a plan that includes your preferred providers or if you’re willing to change providers to access potential cost savings. 

2. Identify any gaps in coverage

A good practice is to identify any limitations or restrictions within the plan. These rules determine how and when you can access certain health care services. By knowing the specifics of your current plan, you can see if there are any restrictions on seeing certain doctors, visiting preferred hospitals or health care facilities, or receiving specialized treatments.  

This awareness will help you evaluate if your current plan matches your preferences and if switching to a different plan with fewer restrictions may be beneficial. 

3. Evaluate the health care needs of you and your family

Your health care plan needs to address you and your family’s care needs. These are a few questions to ask yourself when determining your health care needs. 

  • What sort of services do you use regularly?  
  • Does someone in your family regularly take medications? 
  • Are you expecting any potential health care changes in the next year? 
  • Does anyone have a preexisting condition or congenital disease? 
  • Do you expect your health care needs to change from last year to this year? 

Everyone will have unique needs, so you need to assess what those are to choose a health care plan that fits them. 

4. Consider any potential life changes

It’s difficult to know what your exact health care needs will be in the coming year, so you need to pick a plan that can help cover you in the case of unexpected events. Potential life changes can include unexpected diseases or accidents, but they also include things you plan such as pregnancy or surgery. Insurance is not just for your current medical needs; it also helps protect you so you can get the care you need when life changes occur. 

Plenty of life events can also affect what plan you choose. This includes things like having a baby or adopting a child, getting married or divorced, retirement, moving to a new area, changes in income, or the loss of a spouse or dependent. 

5. Build Wealth with an HRA

CalVEBA’s Journey Plan is a smart, low-cost health care option that helps you save on premiums while staying protected. It includes a Health Reimbursement Arrangement (HRA) through Gallagher’s HealthInvest HRA, which covers qualified medical expenses like deductibles, copays, prescriptions, vision, dental and retiree premiums – all tax free. You receive annual employer contributions, can invest in select funds, and use them now or save for later.* The funds roll over yearly, cover your family, and stay with you even if you change jobs or health plans.

*Plan availability is subject to employer offerings.

6. Evaluate your Medicare benefits

If you have coverage under Medicare, you should be aware of anything that may change in the coming year. There are several key factors to consider that might prompt a change in your Medicare coverage.  

Whether it’s adjusting your prescription drug coverage, finding a plan with a more suitable provider network, seeking better cost-sharing options, or taking the time to evaluate your needs. Looking at these options will help you make an informed decision and select a Medicare plan that best matches your individual health care needs. 

7. Look at any network changes

It’s important to review your health care plan even if you are satisfied with your current one. That’s because there can be changes to the plan or to your network of providers that may affect your care. 

Changes in health care provider networks can impact your access to preferred doctors, specialists, hospitals, or health care facilities. If your current plan no longer includes your preferred providers in-network or if it restricts access to certain health care providers, it may be necessary to explore other plans that offer a broader network and greater flexibility in choosing your health care providers. 

8. Consider alternative therapies and evolving care preferences

As your health care needs evolve, your priorities may shift. We see this as alternative therapies become more popular and have more research to support their effectiveness. 

Consider any changes in your preferences for health care services, such as alternative therapies, preventive care, or specialized treatments. If your current plan doesn’t align with your changing priorities, exploring different plans that offer the services and benefits you value can help ensure you receive the care you desire. 

9. Review dental and vision coverage

Most medical health care plans do not cover adult dental and vision benefits. Children, however, typically have dental coverage under normal health care plans. 

Some people choose to pay out of pocket for dental and vision services. It’s helpful to have an insurance policy in place for dental emergencies. Those with current vision impairment or a history of dental issues will especially benefit from purchasing these plans. 

10. Update your information

To ensure everything goes smoothly during Open Enrollment, ensure that all your contact and personal information is up to date. Look at these items when updating your personal information: 

  • Your name, address, and birthday 
  • Income level 
  • Changes to dependents 
  • Spousal changes 
  • Beneficiary information 

This is also a good time to organize any documents you need like tax returns or name change documents. 

11. Research and compare plan options 

Now that you have an idea of what your current plan offers compared to your changing health care needs, you can start researching and comparing other options. 

These are some of the main things to look at when researching and comparing plans: 

  • The cost of different plans. 
  • The network of providers and hospitals. 
  • Covered services. 
  • Alternative services provided. 
  • Plan Type (HMO, PPO, HDHP, etc.) 
  • Plan ratings and customer service. 

You’re faced with a lot of information when comparing plans, so it can help to take notes and write down any questions you may have.  

12. Calculate the costs of your options

After you’ve calculated the costs of your current plan, you can use it to compare your other options. Look for plans that offer better cost-sharing or lower out-of-pocket expenses, especially if you anticipate frequent health care visits, treatments, or procedures in the coming year.  

Considering your budget and expected health care expenses, you can determine if switching plans will provide you with greater financial benefits. 

13. Consult with an expert

Choosing a health care plan can be confusing, you don’t have to do it alone! There are plenty of experts out there who are well-versed in the world of health care plans and the different terminology who can help guide you. 

Your Benefits Administrator, human resources person or employee benefits specialist can be a great resource to help you discuss your options. You can also contact The CalVEBA Advocacy team – your dedicated health care concierge – to help answer any benefits questions you may have. 

14. Be mindful of the Open Enrollment period

There are specific Open Enrollment dates each year. If you miss the Open Enrollment window, you may not be able to sign up for a plan, or you’ll be automatically renewed for your current plan. The Open Enrollment window may vary slightly depending on your employer. 

Your employer’s Open Enrollment dates are unique. Please contact your Benefits Administrator for more information on your enrollment period to ensure you sign up for coverage within your window. 

15. Review & Save Your Plan Documents

Congratulations! You’ve decided on a plan, signed up for it, and made your first payment. The date your plan goes into effect depends on your insurer and when you signed up. 

Now that you’ve done the most difficult part of choosing a health care plan, be sure to review and save your important new plan documents so you can easily access your explanation of benefits, and have your documents ready come tax season, or if any complications arise. 

If you find this blog helpful in understanding health insurance and the Open Enrollment period, be sure to check out the other blogs in this series for more in-depth information here. 
Assessing a Plan’s Network in Three Steps 

The quality and extent of a health plan’s provider and health care facility network can be a central factor in deciding whether to stay with a health plan or to find a new one. It’s important to have access to the care you need from providers you want while still protecting your budget.  

During Open Enrollment, we recommend you assess your health plan’s network. Does it still work for you? How does it compare to other plans’ networks? Answering these questions may take a little time and research but will give you confidence in your health plan decisions.

Let’s Start with Definitions

In health insurance language, a network is a collection of providers and health care facilities who contract with a health plan to provide services to members at a rate that is less than their usual fees.  

When you get care from an in-network provider or use an in-network facility, you save money. Conversely, out-of-network providers and healthcare facilities are providers and health care facilities that do not contract with your health plan. Generally, you pay more when you go out-of-network. 

Common Terms

Bookmark this blog that defines common health insurance terms to help guide you as you assess and make your decisions this Open Enrollment.

Three Steps to Assessing a Network

Your comfort in seeking and receiving care is very important. Take time to make sure you’re getting the best care you can while still protecting your budget. Following the below three-step review will help you evaluate a plan’s network and if it can allow you to do just that. 

1. Confirm Certifications and Quality Ratings 

When it comes to entrusting your health with a provider, you can’t be too careful. Find out if your provider is a board-certified doctor at CertificationMatters.org. A doctor that’s certified by the American Board of Medical Specialties (ABMS) has: 

  • Earned a degree from a qualified medical school.
  • Had 3 to 7 years of accredited residency.
  • A license from a state medical board.
  • Passed one or more exams administered by a member of the ABMS.
  • Continuing education requirements.

Next, look into your provider’s quality ratings. The National Committee for Quality Assurance (NCQA), for example, measures provider and health plan quality and recognizes high-quality through certain programs. Their goal is to help consumers — like you — find the best care and coverage available. You can search to see if your providers have received NCQA recognition. Do you need to see a specialist? The American Board of Medical Specialists certifies many different specialties and subspecialities that you can verify online.  

2. Word of Mouth Reviews

Standardized quality measurements give you empirical data to make decisions on. However, there’s a lot to be said for other patient reviews. Getting opinions from others on a provider can give you an insight into the more intangible qualities of a physician, like bed-side manner, the office’s customer service, appointment availability, and more. Start by asking your friends, family, and coworkers for recommendations. Then, take the search online to find other patient reviews at: 

3. Out-of-Network Benefits

Evaluating your plan’s network also means understanding the flexibility it offers—including how it supports care outside the network when needed. There may be times when you need to get care from an out-of-network provider or facility. To find out if someone is out-of-network, you can call their office to ask what health plans are accepted or contact The California Schools VEBA Advocacy Team at 888-276-0250 for assistance. 

You can still seek care out-of-network, but you may need to be prepared for the financial impact of that choice. For most plans, if you go out-of-network, you will likely pay more. Some plan types will not cover out-of-network care at all while some cover only a portion of the costs. Look in your Summary of Benefits and Coverage (SBC) to see what your current plan covers or in the SBC of other plans to compare this benefit.  

Supporting You Now and Next Year

During Open Enrollment, take the time to evaluate your plan’s network and how it has worked for you in the past year. Determining the right network coverage is a balancing act of access to top quality and controlling costs. We’re here to help if you have any questions. Call The Advocacy Team at 888-276-0250 or visit CalVEBA.org/Contact.

CalVEBA Resources

MyVEBA Portal

We’re excited to launch our new MyVEBA Portal. Get started with our new MyVEBA Portal here.

Benefit Contacts

For assistance with specific carrier benefits or issues, such as claims or coverage details, visit CalVEBA.org/Benefit-Contacts/.

Get Support

The CalVEBA Advocacy Team is here to assist with health care navigation, including appointment scheduling and quality of care. Call 888-276-0250 or visit CalVEBA.org/Contact for assistance.


If you find this blog helpful in understanding health insurance terms, be sure to check out the other blogs in this series for more in-depth information and insights into the world of health care. 

New Health Plan: Here’s What to Do Next

Selecting a new health plan that is right for your health and budget is an important part of healthy living. Now that you’ve made your selection, there are things you need to do to ensure the transition to the new plan goes smoothly. These steps can prevent disruption to your care, limit out-of-pocket expenses, and help you ​maximize your​ benefits.

Revisit Your Benefits

Refreshing your understanding of what’s covered by your plan is a good idea throughout the year, especially at the start of a plan year. Your best source of information is your health plan’s Summary of Benefits and Coverage (SBC). It’s an easy-to-understand overview of benefits and coverage provided by a health plan. Health insurance companies are required to provide this document for all plan types. We know this document can be intimidating, so we put together a guide defining terms, sections, and key information. You can view the guide here. Familiarize yourself with your plan’s coverage and benefits for the most value and cost savings.

Additionally, you’ll want to check to see if there are any pre-existing condition rules. The Affordable Care Act (ACA) prevents insurers from denying coverage or charging more for pre-existing conditions. But there are exceptions. Grandfathered health plans — plans in place on or before March 23, 2010 — aren’t required to have the same ACA protections. Check to see if your new plan falls in this category and what that might mean for you.

Take Advantage of Online Resources

You don’t have to worry about bringing your plan materials on the go with you. CalVEBA members can access their plan information online through the MyVEBA Member Portal. Register and sign in to:

  • View Your current health plan.
  • Access digital ID cards for yourself or your dependents.
  • Review your Summary of Benefits and Coverage (SBC).
  • Access plan documents and benefit resources.

Transfer Medical Records

Under the Health Insurance Portability and Accountability Act of 1996 (HIPAA), only you or your representative has a right to access your medical records. Providers and health plans can send your information to another provider or plan if it’s needed for care or payment — otherwise, you’ll need to permit them. If you’re changing PCPs, you’ll want to submit a Medical Records Transfer form or Medical Records Release form. Call your PCP’s office, and they can get one to you. 

Choosing the Right Primary Care Provider

Health happens beyond the doctor’s office, but meeting with your Primary Care Provider (PCP) can make all the difference in managing your overall well-being. Your PCP is your go-to resource for preventive care, specialist referrals, and personalized support, ensuring your care is consistent, coordinated, and aligned with your goals.

If your plan is a Health Maintenance Organization (HMO), your PCP will also help manage referrals, ensuring you only receive medically necessary care.

Here’s how to pick your PCP:

  • Contact The CalVEBA Advocacy Team at 888-276-0250 or through an online form. Be sure to have the following information ready:  
    • Name  
    • Date of Birth or Social Security Number  
    • Medical Group 
  • Use our new provider search tool, coming soon!

Is your new plan a Health Maintenance Organization (HMO)? HMOs typically require that you get referrals from your PCP to see specialists. That way, they can coordinate your care and make sure you’re getting what’s medically necessary.

Note: If you don’t select a PCP, one will automatically be assigned to you. You can change your PCP and medical group anytime during the year, but you cannot change your benefits plan.

Update Your Contact Information

Making sure your new plan has the right contact information for you is important. The goal is not to enable the insurance company to contact you unnecessarily. Rather, it’s to make sure that you receive plan information, claims are processed smoothly, and you get timely notifications.

Here When You Need Us

The Advocacy Team is here to help you navigate the healthcare system—whether it’s accessing care, dealing with referrals and prior authorizations, or making the most of your CalVEBA benefits for you and your family. 

If you have any questions, contact The Advocacy Team at 888-276-0250 or submit a contact form. For urgent requests, use the “Urgent” box on the contact form.

Health Happens Every Day 

Your wellness journey goes beyond routine doctor’s visits—good health is about daily choices to nourish and care for your body and mind. Whether you’re cooking a nutritious meal, practicing mindfulness, or getting active, every step counts toward building a balanced, healthy life. 

To help you on this journey, CalVEBA offers resources designed to support your daily health efforts. Explore tips and tools for maintaining a healthy lifestyle and staying on top of your wellness goals.  

Understanding Your Health Plan Coverage 

If you find health insurance confusing, rest assured, you are not alone. From uncommon terms to complex grids of benefits to cost share percentages, many people have trouble fully understanding their health plan coverage. In fact, one study shows that over half of the adults surveyed felt at least one part of their health insurance was difficult to understand. Let’s demystify your health plan by walking through where to find your benefits information and how to decode it. 

Summary of Benefits and Coverage

Your best source of information is your health plan’s Summary of Benefits and Coverage (SBC). It’s an easy-to-understand overview of benefits and coverage provided by a health plan. Health insurance companies are required to provide this document for all plan types so that prospective and current members know their benefits and are also able to compare plans more easily. With that said, there’s still a lot of to unpack in this document. Below you’ll find an explanation of each section. 

Plan Information

The SBC starts with general information about a plan. This includes the type of plan it is, dates the coverage is active, and who is covered. In addition, the introduction directs you to where you can find term definitions that will be used in the document.  

Important Questions

Following the general plan introduction is a section called Important Questions. It clarifies your share of costs for care like your deductible and out-of-pocket maximums. Additionally, this section explains the plan’s use of in-network and out-of-network providers and your access to each. 

Common Medical Events

Next is a grid of common medical scenarios, what you’ll pay for each, and any rules or limitations associated. You can use this section to really get into the nuts and bolts of a plan and determine if its coverage is right for your current health needs and budget.  

Exclusions

Some medical services are not covered by your plan such as cosmetic surgery, long-term care, coverage when you travel, and routine eye care. The SBC will outline what those are and what that means for you. Sometimes what’s not covered is just as important for you as what is so make sure to review this section, too. 

Coverage Examples

People learn differently. To ensure that everyone fully understands a plan, the SBC includes examples of coverage for specific medical conditions or events. One coverage and cost share example may be living with type 2 diabetes and another may be having a baby. 

Prescription Drug Coverage

If a plan includes prescription drug coverage, the SBC will direct you to a formulary or list of covered drugs and cost-sharing to review. Take the time to review that document even if you don’t have any prescriptions as that could change.  

Rights to Continued Coverage

This section lets you know that you have a right to continued coverage unless you move out of the coverage area, don’t pay your premiums, or fraud the insurer. A carrier cannot take away your coverage because of any health issues.  

Your Rights to Continue Coverage: There are agencies that can help if you want to continue your coverage after it ends. The contact information for those agencies is: [insert State, HHS, DOL, and/or other applicable agency contact information]. Other coverage options may be available to you, too, including buying individual insurance coverage through the Health Insurance Marketplace. For more information about the Marketplace, visit www.HealthCare.gov or call 1-800-318- 2596. 

Where and When to Review Your SBC

Now that you know the basics of a SBC, you can review it when you want to confirm your current coverage or compare coverage options. You can access your current plan’s SBC on MyVEBA. With Open Enrollment starting, you should be provided a new one soon. Under the Affordable Care Act, the SBC must be distributed with enrollment forms. If there is an auto-renew of a plan, employers must provide the SBC within 30 days of the plan beginning. Sometimes plans change coverage during the year. You’ll receive a new SBC with those changes at least 60 days in advance. So make sure to review any important plan inform 

Working Together for Your Healthiest Life

If you find this blog helpful in understanding health insurance and the open enrollment period, be sure to check out the other blogs in this series for more in-depth information here. 

Get Support: The VEBA Advocacy Team can help you review your health plan and discuss it with you in depth. Call 888-276-0250 or visit calveba.org/contact for assistance. For urgent requests, use the “Urgent” box on the contact form. 

MyVEBA Portal: Easily view your current health plan information through the online portal.

Benefit Contacts: For assistance with specific carrier benefits or issues, such as claims or coverage details, visit calveba.org/benefit-contacts to contact them directly.    

Keeping Your Health and Budget Covered 

Did you know?

Supporting your health while meeting your budget needs is uniquely challenging in today’s world. With the costs of healthcare projected to rise to a 13 year high, what you’ll pay for care is an essential factor in evaluating a health plan.

Whether it’s your current plan or plans you’re considering, taking the time to understand the total costs of your care can keep both your health and budget covered. 

Itemizing Health Plan Costs 

When you think of costs associated with a health plan, you likely think of what comes out of each paycheck for the monthly premium. Monthly premiums are an important consideration, however, there are other costs to note. These costs include: 

Monthly Premiums

The monthly payment made for an insurance policy.

Deductible

What you pay each year before your health plan shares costs. Review your Summary of Benefits and Coverage (SBC) to see what payments are counted towards your deductible.

Coinsurance

The percentage of costs for care you are responsible to pay and is billed to you after the service is performed by the provider or facility.

Copayment or Copay

The fixed amount you pay for medical services, such as office visits or prescription medicines. It is usually paid at the time of your appointment.

Out-of-Pocket Costs

What you pay for healthcare expenses, including things like deductibles, coinsurance, or copays.

Out-of-Pocket Maximum

The most you will pay for healthcare expenses in a year.

Prescription drug costs

Costs for prescribed drugs depend on what tier the drug is in, whether it’s brand or generic, what pharmacy you go to, and more. 

Consider Cost Balance 

The costs of a health plan need to be considered in relation to each other. Some plan, like High Deductible Health Plans (HDHP), offer a lower monthly premium, meaning you’ll pay less per paycheck. However, you may pay more for care overall if you have significant health needs. Conversely, a plan with higher premiums will usually have lower deductibles, lowering the total amount you’d pay for care over time.

They typically work best for those who use health coverage often and those living with chronic conditions. As you consider the different costs of a health plan, balance the costs with your current health needs to, ultimately, protect your budget.  

Where to Find Cost Information 

Your best source of information is your health plan’s Summary of Benefits and Coverage SBC. It’s an easy-to-understand overview of benefits and coverage provided by a health plan. The SBC gives you a snapshot of what costs you can expect to pay throughout the year for care under your health plan. You can use this document to compare the total costs of care you can expect with each plan you’re considering – if you decide your current plan isn’t right for you or simply want to see your options.  

Questions? We Can Help.  

As you review your plan and maybe other plan options during Open Enrollment, we’re here to help make the process as easy and simple as we can. Reach out to The California Schools VEBA Advocacy Team at 888-276-0250 (Monday-Friday from 8 am – 5 pm).

What is Open Enrollment?

In the United States, most people sign up for health care plans during the annual Open Enrollment. Navigating health care plans can be confusing, so it’s important to be well-informed about your options – whether or not you intend to switch your plan. 

Open Enrollment is a critical window that can affect you, and your family’s health care options for years to come. Looking at health care plans can bring up questions, especially before Open Enrollment. Going in prepared helps to ensure that you make the best choice for you and your family. 

Here’s a comprehensive list of questions and answers to help you easily navigate Open Enrollment.  

What exactly is Open Enrollment?

Open Enrollment is when individuals and families in the U.S. can sign up for insurance plans each year. During this period, you can look at and purchase a plan typically through the Health Insurance Marketplace or your employer.  

When is the Open Enrollment period? 

The Open Enrollment period can vary slightly depending on your employer. Your employer’s Open Enrollment dates are unique. Please contact your Benefits Administrator for more information on your enrollment period to ensure you sign up for coverage within your window. 

Pro Tip: Mark these dates on your calendar so you don’t miss this critical window. 

What changes can I make during Open Enrollment?

Open Enrollment is the time to evaluate your current and future health care needs and make any necessary changes. During this period, you can choose a new insurance company and plan to find one that best suits your changing health care needs. 

You can also renew your health insurance, as well as add or remove dependents or spouses, and adjust your adult vision and dental coverage.  

Do I always need to review my options?

It can be tempting to just stick with the plan you already have. It’s important to review your options each year, even if your budget or health care needs haven’t changed. 

This is because many factors can affect the price and service offered by your insurance provider that are out of your control. Other factors that may impact your health care plan include states changing the prices of certain premiums or having new insurers enter the marketplace.  

Reviewing your options is an important part of being proactive about your health and well-being. 

Who needs to enroll during Open Enrollment?

Every person who is not a dependent should take part in Open Enrollment. That includes whether or not you want to make changes to your existing plan. Open Enrollment applies to you whether you’re purchasing insurance through the marketplace, Medicare, or your employer. 

What terms do I need to know before Open Enrollment?

There are a lot of confusing terms in the world of health care. Here are some of the top ones you should know before Open Enrollment: 

  • Deductible: How much you must spend for covered health services before your insurance company pays anything (except free preventive services). 
  • Copay: A fixed amount of money that an individual is required to pay out-of-pocket for a specific health care service or medication, typically at the time of service.  
  • Coinsurance: A cost-sharing arrangement in health care where the insured individual is responsible for paying a percentage of the covered medical expenses, typically after meeting their deductible.  
  • Premium: Premium refers to the amount of money an individual or entity pays to an insurance company in exchange for insurance coverage. This is usually paid monthly or annually. 
  • Out-of-pocket maximum: The maximum amount an individual is required to pay for covered health care services during a specific period, usually a calendar year.  

What happens if I miss the Open Enrollment period?

If you miss the Open Enrollment, your plan typically automatically renews for the next year. If your current plan is no longer available, you may be enrolled in a similar plan instead. If you don’t currently have a health care plan, you may miss your opportunity to enroll unless you meet certain requirements. 

The restrictions around Open Enrollment can vary depending on the state, income level, and whether you are eligible for Medicare. Native Americans can enroll in a health plan at any time, without needing a qualifying event. 

How do I compare the costs of different plans?

One of the most important factors to consider when choosing a plan is the cost compared to the benefits received. People often just look at the monthly premium, however, there’s much more that goes into the cost of your insurance. 

Besides the premium, some other costs to consider are your deductible, copayments and coinsurance, out-of-pocket maximum, and your estimated health care needs for the year. 

Will I receive new ID cards this year? 

As technology evolves so will your health insurance! No, you will not be receiving your new insurance ID cards in the mail like you typically do. In 2025, all carrier ID cards will be digital.  

You receive more information about your new digital ID cards during Open Enrollment. If you’d prefer a physical ID card, you can still request one from your plan carrier.

How should I prepare for Open Enrollment?

It’s almost Open Enrollment, and being prepared will make this process that much easier. Here a few more things to keep in mind as you prepare for Open Enrollment: 

  • Know how much health care you may need next year, including wiggle room for emergencies or the unexpected. 
  • See if your preferred providers and hospitals are within the network of the plans you’re looking at. 
  • Are you or your family expecting any changing medical needs in the next year such as pregnancy or surgery? 

Once you have a good idea of your budget and health care needs, ask your employee benefits contact for more information on where and when to enroll. With all this information at your fingertips, you’ll be able to easily pick out the best plan for you and your family. 

If you find this blog helpful in understanding health insurance and the open enrollment period, be sure to check out the other blogs in this series for more in-depth information here. 

VEBA Resources  

MyVEBA Portal: Easily view your current health plan information through the .   

Benefit Contacts: For assistance with specific carrier benefits or issues, such as claims or coverage details, visit calveba.org/benefit-contacts to contact them directly.    

Get Support: The VEBA Advocacy Team can help you review your health plan and discuss it with you in depth. Call 888-276-0250 or visit calveba.org/contact for assistance. For urgent requests, use the “Urgent” box on the contact form. 

Living a Heart-Healthy Lifestyle

A heart-healthy lifestyle is important for everyone, not just for people with existing health problems. It can help you keep your heart and blood vessels healthy. If you already have health problems, such as high cholesterol or high blood pressure, a healthy lifestyle can help you lower your risk of a heart attack and stroke.

If you have children, you can be their healthy role model. If your habits are healthy, your children are more likely to build those habits in their own lives.

How can you keep your heart healthy?

Diet

  • Use less salt when you cook and eat. This helps lower your blood pressure. Taste food before salting. Add only a little salt when you think you need it. With time, your taste buds will adjust to less salt.
  • Eat fewer snack items, fast foods, canned soups, and other high-salt, high-fat, processed foods.
  • Read food labels and try to avoid saturated and trans fats. They increase your risk of heart disease by raising cholesterol levels.
  • Limit the amount of solid fat — butter, margarine, and shortening — you eat. Use olive, peanut, or canola oil when you cook. Bake, broil, and steam foods instead of frying them.
  • Eat a variety of fruits and vegetables every day. Dark green, deep orange, red, or yellow fruits and vegetables are especially good for you. Examples include spinach, carrots, peaches, and berries.
  • Foods high in fiber can reduce your cholesterol and provide important vitamins and minerals. High-fiber foods include whole-grain cereals and breads, oatmeal, beans, brown rice, citrus fruits, and apples.
  • Eat lean proteins. Heart-healthy proteins include seafood, lean meats and poultry, eggs, beans, peas, nuts, seeds, and soy products.
  • Limit drinks and foods with added sugar. These include candy, desserts, and soda pop.

Lifestyle changes

  • If your doctor recommends it, get more exercise. Walking is a good choice. Bit by bit, increase the amount you walk every day. Try for at least 30 minutes on most days of the week. You also may want to swim, bike, or do other activities.
  • Do not smoke. If you need help quitting, talk to your doctor about stop-smoking programs and medicines. These can increase your chances of quitting for good. Quitting smoking may be the most important step you can take to protect your heart. It is never too late to quit.
  • Limit alcohol to 2 drinks a day for men and 1 drink a day for women. Too much alcohol can cause health problems.

Healthcare

  • Seeing your doctor regularly and getting screening tests is important. The sooner your doctor diagnoses a disease, the more likely it can be cured or managed. The tests you might have to check your risk for heart and blood vessel problems depend on your age, health, sex, and risk factors. Talk to your doctor to find out which tests are right for you.
  • Managing health conditions, such as diabetes, high blood pressure, and high cholesterol, can help keep your heart and body as healthy as possible.
  • Take your medicines exactly as prescribed. Call your doctor if you think you are having a problem with your medicine.

Validating Your Child’s Emotions